Weekly Comic
Dog-Bite Liability and Home Insurance
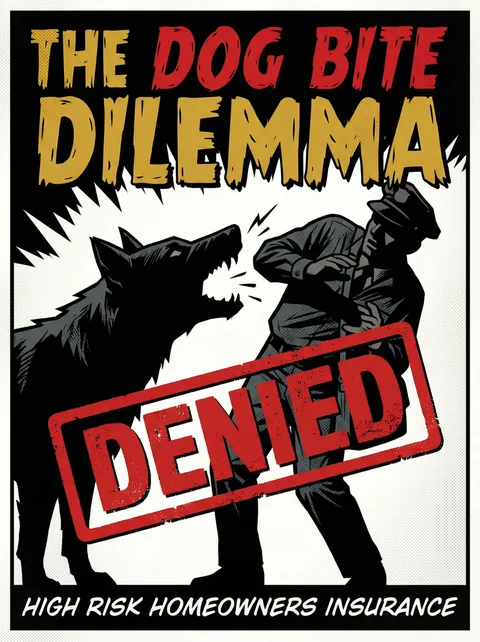
The Dog Bite Dilemma follows a homeowner from a sudden liability incident through the claim, renewal concerns, practical safety improvements, and a specialist's review of available coverage.
Quick answer
Homeowners liability coverage may respond when a dog injures someone, but animal-liability terms vary. A policy may contain exclusions, sublimits, conditions, or restrictions related to a particular animal or prior incident. A claim can affect renewal and future quoting. Secure the animal, help the injured person, document the facts, follow policy notice requirements, and review the exact policy language with a licensed professional.
The Dog Bite Dilemma
Weekly Comic
The incident
A dog gets through an unsecured gate and injures a visitor. The immediate priorities are safety, appropriate medical attention, securing the animal, and preserving the facts of what happened.
Weekly Comic
The liability claim
A homeowners liability claim may involve medical expenses, investigation, legal defense, or a settlement, depending on the policy and circumstances. Coverage is controlled by the actual policy language.
Weekly Comic
The renewal problem
After a bite or animal-liability claim, an insurer may impose conditions, exclude the animal, change terms, or decide not to renew. Other insurers may apply different underwriting rules.
Weekly Comic
Reduce the risk
A repaired fence, secure gates, leash practices, training records, veterinary records, and compliance with applicable animal-control requirements can help document responsible risk management. They do not guarantee coverage.
Weekly Comic
Read the policy carefully
Do not assume every homeowners policy treats animal liability the same way. Review exclusions, limits, endorsements, conditions, and any separate animal-liability coverage before binding.
Weekly Comic
Find the right market
A licensed specialist can present the incident accurately, review mitigation, and compare insurers or specialty markets that may consider the risk. Insurance companies make the final underwriting decision.
Practical next steps
What to do next
- Handle safety first. Secure the dog, assist the injured person, and comply with applicable reporting or animal-control requirements.
- Document the facts. Preserve photographs, witness information, medical communications, training records, and the condition of gates or fencing.
- Review the policy and notice duties. Report the incident as required and avoid making assumptions about coverage before the insurer reviews the facts.
- Address the ongoing risk. Repair containment issues, use professional training where appropriate, and disclose the history accurately when seeking coverage.
Need help after a dog-bite claim or animal-liability restriction?
A licensed high-risk home insurance specialist can review the incident history, mitigation steps, policy restrictions, and currently available markets. Coverage is not guaranteed, and terms vary by insurer and state.
Start a coverage reviewCommon questions
Dog-Bite Liability and Home Insurance FAQ
Does homeowners insurance always cover a dog bite?
No. Coverage depends on the policy, exclusions, endorsements, limits, facts of the incident, and applicable law. Some policies restrict or exclude animal liability.
Will one dog-bite claim automatically cause a nonrenewal?
Not automatically. Insurers use different underwriting rules. The severity, circumstances, prior history, animal, mitigation, and state rules may all matter.
Can an insurer exclude only the dog rather than the entire home?
Some insurers may offer an animal-liability exclusion or other restriction, but availability and wording vary. An exclusion can leave the homeowner personally responsible for future incidents.
Do training and fencing guarantee that coverage will be restored?
No. They may help demonstrate risk reduction, but an insurer still decides whether to offer coverage and on what terms.
Should I disclose a prior bite or animal-liability claim?
Answer application questions accurately and completely. Misrepresentation can create serious coverage and rescission problems.
Can separate animal-liability coverage be available?
In some situations, a specialty policy or endorsement may be available. Limits, exclusions, eligibility, and pricing vary.
Editorial note: This weekly comic provides general educational information. It is not an insurance policy, binder, quote, coverage offer, legal opinion, or guarantee of eligibility. Actual policy language controls. Underwriting rules, pricing, coverage, eligibility, and availability vary by insurance company and state and may change. Review your specific documents with a licensed insurance professional.
Last reviewed: September 21, 2026.